All the Lanes, w/ Ashley Puckett
Hello and welcome back to The MikedUp Show! Part of my identity is going to mortgage conferences. Part of this show's job is to bring you the people who go to those conferences so you don't have to. And lately the requests have all been pointing at one seat: capital markets. The headlines are nothing but rates and affordability, everybody wants to know whether they'll ever get back to the rate they've got, and the person who actually decides what shows up on your rate sheet is almost never the person you get to hear from.
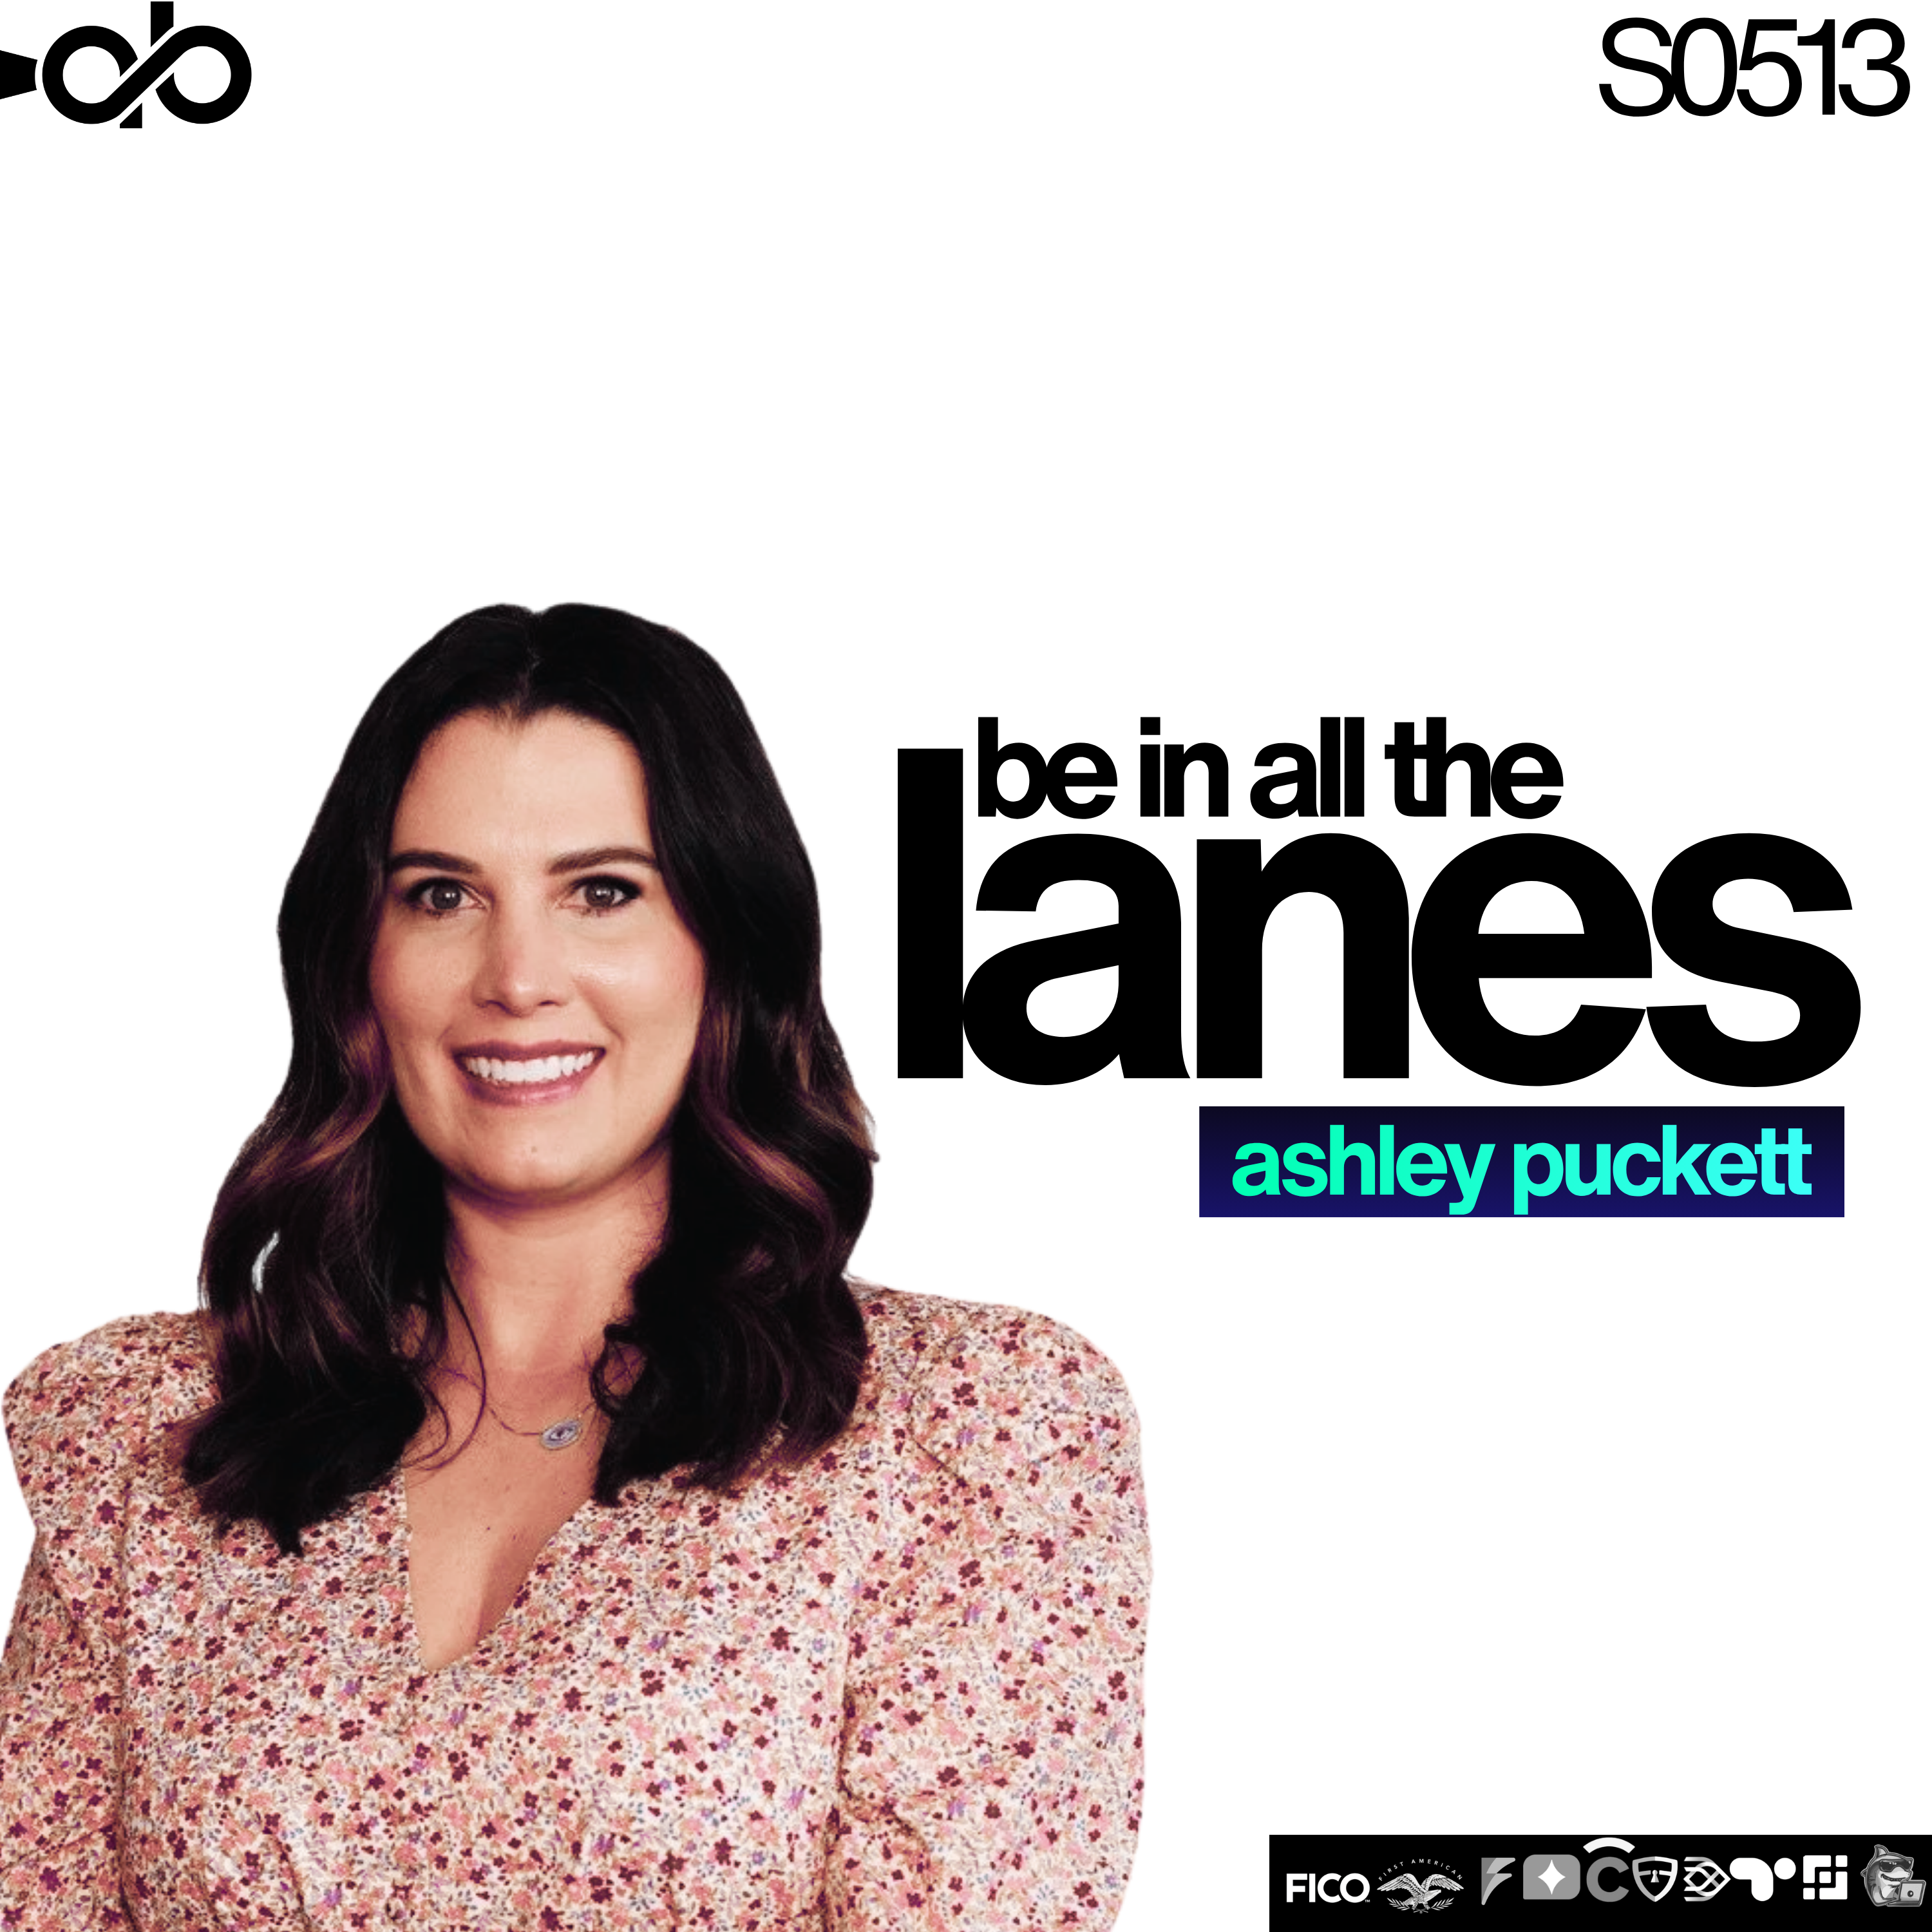
So this week I sat down with Ashley Puckett, CMB, AMP, AVP of Capital Markets at Novus Home Mortgage. I've run into Ashley for years on the circuit, especially at Secondary in New York, which is where the capital markets crowd goes. She's an Army kid who grew up partly in Germany and partly around Augusta, Georgia, spent nine and a half years at AmeriSave, and got to the trading desk by a route almost nobody plans on purpose. If you've ever been curious about what the desk knows that you don't, this one's for you.
Truework is the only all-in-one, automated VOIE platform that fully replaces costly in-house verification waterfalls by orchestrating all major verification methods within a single platform. With an industry-leading 75% completion rate, we have helped mortgage providers achieve up to 50% cost savings on their verification process, resulting in multi-million dollar savings. Looking to save on verification costs while improving borrower experience and pull-through? Let’s talk.
THE LANE NOBODY PLANS: FROM POST-CLOSE TO THE TRADING DESK
Most people on a lock desk didn't come up through operations. Ashley did. Six months in processing, then post-closing, where she ran QC audits, worked investor conditions, and helped build the delivery guides. Then secondary, then capital markets. It isn't the usual route and she wouldn't trade it: "I actually love my path." [29:49] It gave her a base of knowledge on both ends of the transaction, the front and the back, and she can still open a file today and know exactly what she's looking at. That matters when she's coaching people on her team who've only ever sat at a lock desk.
Friday Harboris an AI pre-underwriting platform that helps loan teams convert more of the opportunities already in their pipeline by identifying and resolving income, asset, credit, appraisal and documentation issues before files ever reach underwriting.
The impact is measurable. Loan teams using Friday Harbor report a seven-point increase in applications reaching underwriting, with FHA loans, HELOCs and borrowers in the 80-90% LTV range seeing double-digit improvements.
Trusted by leading lenders likeNewFed Mortgage, Longbridge Financial, PRMG, and American Pacific Mortgage, Friday Harbor offers out-of-the-box integrations with leading loan origination systems including Encompass, Calyx Path, and MeridianLink Mortgage.
See how much pull-through you're leaving on the table. VisitFridayHarbor.ai.
It also bought her something you can't teach, which is empathy for the file. "Sitting in that seat and knowing what they go through," she said. "You have a borrower. This is the biggest transaction of their life." [27:32] Held up by two or three conditions, waiting on documentation, sitting there on pins and needles. That memory shows up in how she builds product now. The goal is to put out something that doesn't come back with twenty line items of conditions attached, because every one of those is a real person waiting.
AI shouldn’t just answer questions. It should help you get the work done.AskBobAII puts AI to work across your mortgage operations and beyond—helping teams search, review documents, streamline QC, take action, and automate everyday workflows, all from one intelligent platform. See what happens when AI moves beyond answers and starts doing the work. Imagine What’s Possible with AskBobAI.
GOLDEN HANDCUFFS, AND THE DOOR THAT'S STILL OPEN
I asked Ashley what the headwinds look like from where she sits, and she started where the industry keeps starting: first-time buyers. It's genuinely hard right now for people in their twenties and early thirties to get into a home. Rates are where they are, and values ran up through the COVID years on top of that. "We're having a huge affordability crisis." [4:21] We need those buyers and we want them, and the math is working against them.
TRUEhelps lenders automate mortgage document intake, borrower document analysis, QC, post-close review, and risk monitoring through an enterprise AI platform designed to remove manual work, not just redistribute it. Today, more than 1,000 mortgage professionals use the TRUE MOS platform, and their blended AI helps process over 600,000 loans annually across origination, underwriting, quality control, and post-close operations. If you're looking to increase throughput, improve operational efficiency, and scale without adding headcount, visitTRUE.aito learn more.
Then there's everybody who already owns. "People are stuck." [5:20] Nobody's giving up a three percent or three and a quarter note rate, even when they've got real equity sitting in the house and a reason to use it, whether that's home improvements, a kid heading to college, or an emergency. So the door that's still open is the second lien, and the industry has noticed. Ashley's seeing an uptick across originations, with lenders leaning into that business model and making it a bigger share of overall production. [5:36] If you've been treating seconds as an afterthought, the capital markets desk is already telling you otherwise.
Addy AI helps mortgage teams close loans faster with AI agents built for lending.From document review and borrower document requests to condition resolution,guideline answers, and loan prep, Addy AI automates the manual work that slows down loan officers and processors. Addy integrates with the mortgage tech stack and is SOC 2 Type II compliant for enterprise teams. Book a demo ataddy.com.
WHAT THE DESK KNOWS AT EIGHT THAT THE FIELD LEARNS AT NOON
So what does the morning actually look like? She opens the nightly reports from MCT, their hedge analytics provider, and reads the position: where did we come in overnight, do I need to put coverage on this morning or can it wait, what does fallout look like, are there loans that aren't pricing out and need updating so the mark-to-market on the pipeline isn't wrong. [25:57] Then economic news lands around eight fifteen or eight thirty, before investors publish their rate sheets.
That's the gap. Loan officers have MBS Live and market commentary, but the desk is watching a live market screen in real time, and then working the phones. Ashley says the Atlanta capital markets community is tight across competing companies, in constant communication, running a lot of the same systems: are we sliding or rallying, do we pivot right now, do we delay pricing for the day, do we turn pricing off? Her read is that it ends up helping everybody's loan officers, not just hers. But the field doesn't see any of it until the rate sheets are out and there's open pricing to lock.
FundingShieldis the market leader in embedded wire and title fraud prevention, closing agent vetting, and compliance automation. With over $4.5 trillion in mortgage and real estate transactions protected, our solutions deliver unmatched security and efficiency. Lenders rely on our real-time, source-verified, decision-ready data to safeguard funds, streamline workflows, and reduce operating costs across closing and title workflows. Contactsales@fundingshield.comto discover how we can help you close with confidence.
EVERYBODY IN THIS BUSINESS IS SOMEBODY'S CLIENT
I tell people at these conferences that loan officers are the mortgage company's customers, because the cost of acquisition just isn't low enough to think otherwise. Ashley says it plainly from her side: "They are our client." [10:34] That means picking up the phone, running a screen share, walking a scenario in Optimal Blue that won't price. Is there an exception here? Can we rework the file? Maybe we're not looking at the right product and this is a non-QM loan, not an agency loan. Her team is small enough that branches get what she calls "small IMB service" from a company forecasting three and a half billion. [16:08]
SharkeyByte gives mortgage lenders one platform to replace a growing stack of disconnected Encompass tools, automation vendors, analytics products, and custom utilities. Built specifically for lenders using Encompass®, the SharkeyByte Platform combines 129+ production-ready Desktop tools, Web Plugin capabilities, Ocean workflow automation, and Deep Dive operational intelligence in one solution.
Recommended by LinkedIn
Graham's List Has Three Things On It. Two of Them…
                Chris Black


  2 months ago
What Are We Counting in Mortgage Manufacturing Costs
                Brian Vieaux, CMB


  2 months ago
Why Pylon matters more than most mortgage executives…
                Chris Black


  6 months ago
Teams use SharkeyByte to automate repetitive work, streamline loan and eFolder processes, improve Encompass productivity, identify operational bottlenecks, measure labor and system performance, and deploy workflows without managing a separate vendor for every problem.
SharkeyByte is designed to make Encompass easier, teams faster, and mortgage technology simpler to manage.
One platform. More automation. Better visibility. Fewer vendors.
VisitSharkeyByte.comto see what your operation could consolidate.
Then she flips the relationship, and this is the part most originators never see: "I'm the client of the investor." [11:27] Monthly calls, scorecards showing investors where they stacked up on volume and pricing, and steady pressure on review times and first-pass rates so loans get purchased and off the warehouse lines. Investors always want more volume. The counter is speed, and everything lands on best execution. She keeps the whole field current with a monthly Talk the Lock series where loan officers submit topics ahead of time and the chat stays open for the rest
Sei AI builds AI agents that actually do the work in your shop — not another chatbot, but agents that read the file, clear conditions, and move loans forward. Their Origination & Underwriting Assistant works your stips at machine speed. Helping Nasdaq listed lenders reduce manual review time by 75%.
Their voice agents handle borrower calls around the clock, helping lenders double qualified leads.
It's all built for regulated lenders, which is why production teams at banks & listed IMBs run on Sei AI today. If your ops team is drowning in manual work, go see what an agent can take off their plate.
MIKED UP SHOWS HERE: Please subscribe.
COFFEE AT NINE, THE MARKET AT NINE THIRTY
Her team is spread out, and she doesn't think that has to cost you anything as long as you work at it. Every morning at nine Eastern there's coffee talk, and the rule is that it's about everything that isn't mortgage. What are you doing this weekend, how are the kids, how was the baseball game. [13:36] Then at nine thirty the team call: what's on for today, what didn't get resolved yesterday, how do we prep. She isn't sitting in the corporate office and she still feels connected to her team, which is the whole point.
First American ACI, a member of the First American family of companies, delivers innovative valuation technology that helps real estate appraisers work efficiently, accurately and confidently. Its cloud-based ACI Sky™ Workbench has completed software verification for UAD 3.6 -- an important milestone for appraisers preparing for the redesigned Uniform Residential Appraisal Report (URAR). Since 1979, ACI has helped appraisers navigate industry change with trusted valuation technology. Today, ACI supports valuation professionals and organizations of all sizes, from independent appraisers and appraisal firms to AMCs, lenders, and servicers in the United States and Canada. Is your appraisal partner ready for UAD 3.6 on November 2, 2026? Visithttps://www.aciweb.com/beready/to download our free Readiness Checklist created for lenders and appraisers.
The rest is education, and Ashley is unusually direct about why she collects it. The certified mortgage banker and the accredited mortgage professional designations were about "giving back to the industry" and being a resource for anyone who needs one. [8:20] But listen to what she says the real payoff was: "I've met some of my industry best friends doing it… And I have their cell phone numbers. I can call. I can text at any time." [9:24] The designation is a credential. The network behind it is a phone list. She calls herself a connector, says she has friends in every facet of this business, and if she can't answer your question she knows who can.
CLOSING THOUGHT:
I asked her to finish a sentence for every processor and post-closer listening: the fastest way out of your lane is what? "Be curious, ask questions, go to the departments." [34:50] If you're in processing and you want to understand underwriting or closing, walk over and ask somebody to show you. That's what she did, and it's how a processor ends up on a trading desk.
A word on the shop, since we try to be a place for transparency about the companies in this industry. Novus Home Mortgage is a division of Ixonia Bank, a small privately held bank in the Milwaukee area, which means licensure in all fifty states and a wide product set with an investor relations group always hunting the next outlet. [36:46] Ashley's pitch is the exec team: direct access to the top at a company this size, which is rarer than it should be. And for the exception-story collectors, she brought one back from her credit risk lead. A loan originator once asked to close the loan without the appraisal and go get it afterward. Hard no. Some lanes you don't get to change.
“70+ lenders have already signed up for theFICO ® Score 10T Free Access Program — a path to test the credit score built for today's risk landscape. Built on trended credit data, FICO Score 10T helps lenders identify more qualified borrowers without adding risk. See why leading lenders are signing up and start testing it on your own portfolio for free.”
Full episode
To hear more lively discussions and special guest insights in the realm of mortgages and real estate, check out TheMikedUp Show with Mike Kelleher and Michael Zau, every Thursday at 2pmET!
THE ABOVE IS A SUMMARY OF INSIGHTS & ANECDOTES TAKEN FROM AN HOUR-LONG PODCAST EPISODE OF THEMIKEDUP SHOW. MIKE & MIKE RESERVE THE RIGHT TO PARAPHRASE WHEREVER NECESSARY.
Listen to the full episode on The MikedUp Show
Originally published in Michael Kelleher's LinkedIn newsletter
Host/CEO, Adopt The Brand
I pioneered white label mobile apps in the mortgage industry that processed over $500 billion in loan volume and served 32,000+ loan officers.
For the past decade, I've navigated the complex intersection of mortgage and technology:
Built relationships with 200+ IMB CEOs, 20 banks, and 15 credit unions
Sold over $10M in SaaS contracts to an industry resistant to change
Sold over 20 million in annual contracts of services.
Managed product roadmaps and legal frameworks for enterprise integration of other contratsions
Attended 155+ industry conferences, building an unmatched network
I don't just open doors—I build bridges between innovative tech and mortgage leaders who need solutions.
When we work together, you get:
A translator who converts your tech-speak into mortgage value
Implementation strategies that actually work in the real world
Direct access to decision-makers you'd otherwise spend 6+ months trying to reach
My weekly show connects industry leaders and showcases emerging solutions, while my consulting helps companies avoid the $250,000+ mistake of approaching the mortgage market incorrectly.
The mortgage industry doesn't need another shiny app. It needs systems that truly integrate with how lending works.