Technology Is a Portion of the Recipe
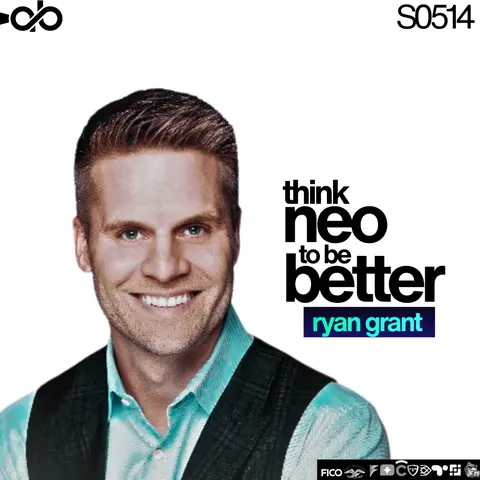
Hello and welcome back to The MikedUp Show! This one is a return visit, which is one of our favorite kinds of episode. You get to pick up where you left off and find out what actually happened to the plan. Mike guessed it had been nine months since Ryan Grant was last with us, then hedged and said maybe six. Either way, a lot's moved.
Truework is the only all-in-one, automated VOIE platform that fully replaces costly in-house verification waterfalls by orchestrating all major verification methods within a single platform. With an industry-leading 75% completion rate, we have helped mortgage providers achieve up to 50% cost savings on their verification process, resulting in multi-million dollar savings. Looking to save on verification costs while improving borrower experience and pull-through? Let’s talk.
Here's the frame Mike keeps putting on this show, and it runs through the whole hour. Everybody is focused on disclosure to closing. The people actually taking market share are working the part nobody watches, and that's everything that happens before the disclosure. How do you find the renter who's ready to own? The family having another kid who needs another bedroom? The borrower coming home from deployment with a VA loan? Ryan built a company around that question. He spoke at Adopt The Brand a couple of weeks before we recorded, and he'll be back on stage at Adopt The Brand Day in 2027.
THE HYPOTHESIS GETS LOUDER WHEN RATES GO UP
Ryan opened with his own read on why people are suddenly curious about him. "my hypothesis is probably louder today than it has been because of the interest rate environment that we are in." Then he said the part people leave out when they quote him. In an easier market, a more emotionally stable one for buyers and sellers, he thinks this industry could keep doing exactly what it's done for seventy-five years and be fine. It's the other market that changes the math. "in an environment where everybody is very scared or nervous or curious that is when the elevated mortgage advisor is needed now more than ever."
Friday Harboris an AI pre-underwriting platform that helps loan teams convert more of the opportunities already in their pipeline by identifying and resolving income, asset, credit, appraisal and documentation issues before files ever reach underwriting.
The impact is measurable. Loan teams using Friday Harbor report a seven-point increase in applications reaching underwriting, with FHA loans, HELOCs and borrowers in the 80-90% LTV range seeing double-digit improvements.
Trusted by leading lenders likeNewFed Mortgage, Longbridge Financial, PRMG, and American Pacific Mortgage, Friday Harbor offers out-of-the-box integrations with leading loan origination systems including Encompass, Calyx Path, and MeridianLink Mortgage.
See how much pull-through you're leaving on the table. VisitFridayHarbor.ai.
Mike asked what this rate environment has changed about how Ryan thinks about building. The answer was nothing, and that's the point. His group doubled down on the same philosophy, which is "being the most important and the most valuable person in our clients lives when it comes to real estate or finance for ninety two percent of America who doesn't have a financial planner" or a CPA or a bunch of attorneys standing around them. From where we sit, that's him making the same bet twice, louder. Ryan's version of the problem is smaller than it sounds: "We just need to be louder about it so more people can hear us."
TECHNOLOGY IS A PORTION OF THE RECIPE
“70+ lenders have already signed up for theFICO ® Score 10T Free Access Program — a path to test the credit score built for today's risk landscape. Built on trended credit data, FICO Score 10T helps lenders identify more qualified borrowers without adding risk. See why leading lenders are signing up and start testing it on your own portfolio for free.”
He won't say loan officer, and he told us why before he answered anything. "I'm not a fan of the term loan officer." He says mortgage advisor, because we should probably call ourselves what we want to be known as. Then he laid out a recipe for being one of the most effective and sought after mortgage professionals in the market, and put the thing everybody fixates on in its place. "technology is just a portion of that recipe." What it does is remove friction, let you help more families, and keep your team in the genius zones where they get a high return on energy.
AI shouldn’t just answer questions. It should help you get the work done.AskBobAII puts AI to work across your mortgage operations and beyond—helping teams search, review documents, streamline QC, take action, and automate everyday workflows, all from one intelligent platform. See what happens when AI moves beyond answers and starts doing the work. Imagine What’s Possible with AskBobAI.
There's product capability in the recipe underneath it. Helping agents and builders market the inventory that exists right now. First party lead generation. Two operating modes the technology protects: business development, then consultation. More time asking better questions, taking fear and uncertainty out of the room, educating people toward one of two paths, which Ryan puts as buy or sell now, or buy or sell later. And what powers all of it is a mindset, in his words, "that we are so much more than anybody has ever expected us to be." Once a client's worked with somebody operating that way, he says, they'll never go back.
MIKED UP SHOWS HERE: Please subscribe.
WHO DO THE NINETY-NINE PERCENT GO TO?
Mike brought up the straw man, the headline version of Ryan that reads like the death of the LO. Ryan's answer was that the debate should happen in the open. After his panel at the New England Mortgage Bankers Conference, somebody told him a guy in the hallway had called the whole thing BS. No time, no training, the consumer doesn't want it. Have that argument out loud, Ryan says. "we need to stop saying what will or won't work behind each other's backs." Then he named the thing the trade press never covers while it covers acquisitions and platforms: "we absolutely will lose to an AI chatbot if we continue down the path of quote rates, close loans."
TRUEhelps lenders automate mortgage document intake, borrower document analysis, QC, post-close review, and risk monitoring through an enterprise AI platform designed to remove manual work, not just redistribute it. Today, more than 1,000 mortgage professionals use the TRUE MOS platform, and their blended AI helps process over 600,000 loans annually across origination, underwriting, quality control, and post-close operations. If you're looking to increase throughput, improve operational efficiency, and scale without adding headcount, visitTRUE.aito learn more.
Michael pushed on the cookie cutter borrower, the one DU and LP can run straight through with the loan officer cut out of it. Ryan backed up a step. Anybody uploading documents into a lending portal has already decided to buy or refinance. If you're meeting them there, then yes, be the cheapest, because they did all the mental gymnastics without you. His test is what happens earlier. Survey ten thousand homeowners about their plan at seven and a half percent and "you would get less than one percent that would give you any substantive plan." So who do the rest call? "The answer is no one except maybe a family member because they're sure as hell not going to call a realtor or a lender because they don't call us until they're ready because they know we're salespeople." His conclusion: "it's not a tech thing. It's a messaging thing. It's an availability thing. It's a value thing."
Addy AI helps mortgage teams close loans faster with AI agents built for lending.From document review and borrower document requests to condition resolution,guideline answers, and loan prep, Addy AI automates the manual work that slows down loan officers and processors. Addy integrates with the mortgage tech stack and is SOC 2 Type II compliant for enterprise teams. Book a demo ataddy.com.
EIGHTY PERCENT PART-TIME IS A LEADERSHIP PROBLEM
First American ACI, a member of the First American family of companies, delivers innovative valuation technology that helps real estate appraisers work efficiently, accurately and confidently. Its cloud-based ACI Sky™ Workbench has completed software verification for UAD 3.6 -- an important milestone for appraisers preparing for the redesigned Uniform Residential Appraisal Report (URAR). Since 1979, ACI has helped appraisers navigate industry change with trusted valuation technology. Today, ACI supports valuation professionals and organizations of all sizes, from independent appraisers and appraisal firms to AMCs, lenders, and servicers in the United States and Canada. Is your appraisal partner ready for UAD 3.6 on November 2, 2026? Visithttps://www.aciweb.com/beready/to download our free Readiness Checklist created for lenders and appraisers.
Michael came at the same gap from the regulatory side, and it's the sharpest thing anybody said all hour. A Series 7 advisor who moves a client out of stocks and into housing is selling away under FINRA, so they can't do it. A mortgage advisor is licensed to originate debt, not securities, and can give a homeowner real guidance about housing the way you would at a barbecue. We've got the lane. Almost nobody drives in it. So should individual IMBs test their own people on advice, Michael asked, instead of testing them on fair lending and jail sentences? Ryan: "I think this is largely a leadership problem." He started in 2005, when nobody on the planet was mentoring a mortgage professional on financial literacy. The people who ran great origination shops then went on to found the companies that are massive now, and nobody mentored them on it either.
FundingShieldis the market leader in embedded wire and title fraud prevention, closing agent vetting, and compliance automation. With over $4.5 trillion in mortgage and real estate transactions protected, our solutions deliver unmatched security and efficiency. Lenders rely on our real-time, source-verified, decision-ready data to safeguard funds, streamline workflows, and reduce operating costs across closing and title workflows. Contactsales@fundingshield.comto discover how we can help you close with confidence.
His recommendation is a CFP-style designation with a hard test behind it. Financial literacy, generational wealth, personal finance. He wouldn't use it as a gate, because there's always going to be a place for the discount shop. He'd put real marketing dollars behind the people who pass. Picture three licensed professionals, he says. One holds the designation and fiduciary standing, "which no one in the mortgage industry is, which is a problem." One sits in the middle. One is a part-time 1099 contractor who closes a mortgage every four months, "which is like eighty percent of our industry, by the way." Run the math on what that means for the consumer's next phone call. Ryan already has: "That's when they just ask chat or Claude. And I would encourage them to do that as opposed to the alternative." He's right, and it ought to sting a little.
THIRTY YEARS, NOT THIRTY DAYS
The decision that reorganized his team is worth quoting whole. "we won't be a dollar more expensive than the cheapest lender in the country unless we can quantifiably show our clients how valuable we will be in their life." Everything after that is the work of earning the dollar. He's honest about why it's hard. People in or near a transaction are hyper-emotional, and they're emotional about black and white figures. The payment is the logical number. The rate is the emotional one, and the reason is social: "the last thing you want to do is go to a barbecue and, you know, everyone's talking about, oh, I just bought a house. So I got a seven and a half. I have a four. Like, you just feel dumb." You feel dumb because your loan officer never taught you anything.
SharkeyByte gives mortgage lenders one platform to replace a growing stack of disconnected Encompass tools, automation vendors, analytics products, and custom utilities. Built specifically for lenders using Encompass®, the SharkeyByte Platform combines 129+ production-ready Desktop tools, Web Plugin capabilities, Ocean workflow automation, and Deep Dive operational intelligence in one solution.
Teams use SharkeyByte to automate repetitive work, streamline loan and eFolder processes, improve Encompass productivity, identify operational bottlenecks, measure labor and system performance, and deploy workflows without managing a separate vendor for every problem.
SharkeyByte is designed to make Encompass easier, teams faster, and mortgage technology simpler to manage.
One platform. More automation. Better visibility. Fewer vendors.
VisitSharkeyByte.comto see what your operation could consolidate.
So Neo rebuilt the client presentation around a different question. You'll own a house. Do you know what to do with it for the next thirty years? Estate planning, the right insurances, what happens when there's a death or an inheritance or a kid going to college, tax strategy, buying real estate for your children. Every single person says no. "ninety nine out of one hundred people believe that's their responsibility as a homeowner to figure those things out. We believe it's ours." The proof came from a client who'd just watched a broker beat Ryan by three eighths of a point. She turned to her husband: "if this team's gonna do all that, we're not shopping anyone." That same thinking is how he describes the distribution side, which he calls mortgage as a platform. Ten thousand people a month come to Neo directly. Partnerships with Credit Karma, Coinbase and OpenAI are the front door, and ask ChatGPT for the best online lender and "We come up number one every time." Plenty of those people still reply stop when a human reaches out, so the team sends a link with something useful instead, and watches them come back.
Sei AI builds AI agents that actually do the work in your shop — not another chatbot, but agents that read the file, clear conditions, and move loans forward. Their Origination & Underwriting Assistant works your stips at machine speed. Helping Nasdaq listed lenders reduce manual review time by 75%.
Their voice agents handle borrower calls around the clock, helping lenders double qualified leads.
It's all built for regulated lenders, which is why production teams at banks & listed IMBs run on Sei AI today. If your ops team is drowning in manual work, go see what an agent can take off their plate.
Closing Thought
We finished with three answers, three quick answers. Advice to the version of himself who's still originating: go where the opportunity is biggest, which he says is helping builders and agents manufacture affordability in their own product. One book: The Infinite Game by Simon Sinek, which he credits for getting him out of what he calls the high school cafeteria our industry runs on LinkedIn, where everyone's scoring who is number one this week. Then Mike threw in one that wasn't on the list. Thank 2015 Ryan. The answer came back fast. Mentorship. 2015 was the first year he understood you could have a coach, and it's the year he went from "a good mortgage hobbyist to a good mortgage business owner."
His closing message to anybody who can't get to the conferences was to create curiosity or stay curious. "Just because we've done something for seventy five years the same way doesn't mean we should double down on it for the next seventy five." He knows what the pushback sounds like. You can tell him a thousand reasons he's full of it. His counter is one question: what if he's right? To be frank, you don't have to buy the model to take the question with you. Nobody in this business has a good answer for who a confused homeowner is supposed to call. Ryan has one. That's the whole argument.
Full episode
To hear more lively discussions and special guest insights in the realm of mortgages and real estate, check out TheMikedUp Show with Mike Kelleher and Michael Zau, every Thursday at 2pmET!
THE ABOVE IS A SUMMARY OF INSIGHTS & ANECDOTES TAKEN FROM AN HOUR-LONG PODCAST EPISODE OF THEMIKEDUP SHOW. MIKE & MIKE RESERVE THE RIGHT TO PARAPHRASE WHEREVER NECESSARY.
Listen to the full episode on The MikedUp Show
Originally published in Michael Kelleher's LinkedIn newsletter
Host/CEO, Adopt The Brand
I pioneered white label mobile apps in the mortgage industry that processed over $500 billion in loan volume and served 32,000+ loan officers.
For the past decade, I've navigated the complex intersection of mortgage and technology:
Built relationships with 200+ IMB CEOs, 20 banks, and 15 credit unions
Sold over $10M in SaaS contracts to an industry resistant to change
Sold over 20 million in annual contracts of services.
Managed product roadmaps and legal frameworks for enterprise integration of other contratsions
Attended 155+ industry conferences, building an unmatched network
I don't just open doors—I build bridges between innovative tech and mortgage leaders who need solutions.
When we work together, you get:
A translator who converts your tech-speak into mortgage value
Implementation strategies that actually work in the real world
Direct access to decision-makers you'd otherwise spend 6+ months trying to reach
My weekly show connects industry leaders and showcases emerging solutions, while my consulting helps companies avoid the $250,000+ mistake of approaching the mortgage market incorrectly.
The mortgage industry doesn't need another shiny app. It needs systems that truly integrate with how lending works.